Insurance write-off categories explained: Cat A, B, S and N
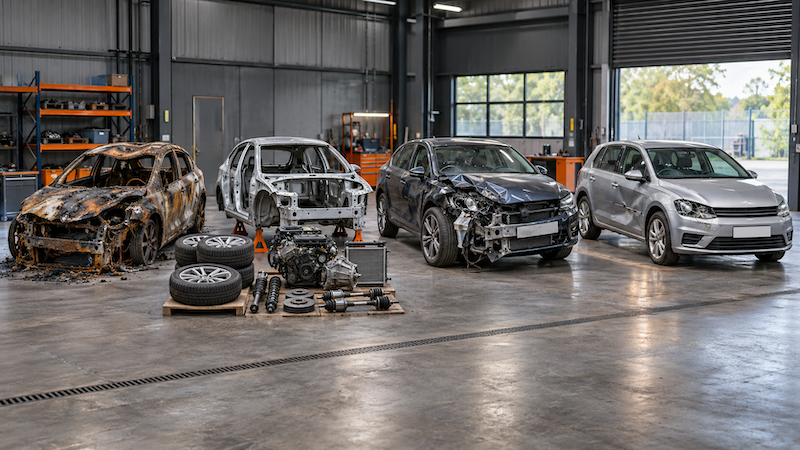
Trade buyers must distinguish repairable stock from vehicles destined for destruction across four UK insurance write-off categories, as defined by GOV.UK’s write-off guidance.
Dealers, insurers and finance teams need clear definitions when reviewing vehicle history reports and assessing vehicles against their buying, lending and insurance criteria.
This guide covers the current and legacy labels, the auction labels U and X, how each category affects value, and how businesses access the records behind them.
Insurance write-off categories at a glance
- Cat A and Cat B: A vehicle in either category can never return to the road.
- Cat S and Cat N: Both are repairable; S covers structural damage and N covers non-structural damage.
- Cat C and Cat D: Pre-October 2017 write-off labels based on repair cost, which do not convert directly to the current Cat S and Cat N.
What are UK insurance write-off categories?
Four categories sort every vehicle that a UK insurer writes off into scrap or repairable salvage. Category A requires crushing the entire vehicle; Category B allows recovery of suitable parts. Categories S and N identify structural and non-structural damage, with reuse conditional on roadworthy repairs, according to GOV.UK.
Each category carries a practical implication for trade buyers:
| Category | What it means | Can it return to the road? | Key implication |
|---|---|---|---|
| A | Scrap the entire vehicle | No | Crush the whole vehicle |
| B | Break for suitable reusable parts | No | Crush the bodyshell |
| S | Repairable structural damage | Yes, once roadworthy | Assess structural repairs |
| N | Repairable non-structural damage | Yes, once roadworthy | Assess required repairs |
How insurance write-off categories changed in October 2017, from Cat C and D to S and N
S and N replaced C and D on 1 October 2017 under the revised Salvage Code of the Association of British Insurers (ABI). Classification moved from judging repair cost to judging whether the damage is structural, as Thatcham Research’s announcement documents. Thatcham Research acted as the code’s technical author.
Category C meant repair costs exceeded the vehicle’s value; Category D meant the vehicle was cheaper to repair than replace, yet the insurer still wrote it off. Auto Trader gives both definitions.
Legacy records retain their original labels. Businesses shouldn’t infer structural damage solely from an old Category C designation.
What auction categories U and X mean for insurance write-off checks
Two labels that appear at auction, U and X, sit outside the ABI’s insurance write-off categories. Copart describes U as used, unrecorded stock and X as stolen and recovered stock with minimal damage. These labels have different meanings from S and N, under Copart’s auction definitions.
Auction buyers should check the operator’s definitions, lot description and damage evidence. Unrecorded stock still warrants examination for accident damage or mechanical faults.
How the Cat S and Cat N write-off categories differ
Category S identifies repairable structural damage; Category N covers repairable damage outside the structural framework or chassis. Category N can still involve safety-critical components needing replacement. The letter doesn’t establish repair quality or current roadworthiness, under the distinctions in the ABI’s Salvage Code.
Trade appraisals should examine the damage evidence, repair method and documented repair quality before setting a purchase price.
How insurance write-off categories affect valuations
Disposal routes and valuation assumptions both follow a vehicle’s write-off category. Category B stock offers parts recovery; repairable stock also offers potential resale. Predicted salvage auction bids reflect the identified vehicle, category and primary damage inputs, as SalvageGuide Bid Predictor’s documentation describes.
| Category | Low bid | Average bid | High bid |
|---|---|---|---|
| B | £320 | £600 | £1,347 |
| S | £1,074 | £1,498 | £2,282 |
| U | £1,112 | £1,739 | £2,812 |
| N | £1,510 | £2,028 | £2,787 |
| X | £2,198 | £3,154 | £4,074 |
Source: SalvageGuide Bid Predictor 16 October 2026 for 2019 Land Rover Range Rover Velar 2.0 D180 R-Dynamic S Auto 4WD Euro 6 5dr with 85,000 miles
Predictions estimate what buyers may bid at auction, so the specific damage and expected repair costs should still inform each appraisal.
Repaired write-offs can also achieve lower retail values: Auto Trader notes that Cat S and Cat N vehicles are usually worth much less than identical vehicles that have never been written off.
How insurance write-off categories are recorded and checked
An Appropriately Qualified Person assesses each total-loss vehicle and assigns its category. Insurers or self-insured organisations record it on the Motor Insurance Anti-Fraud and Theft Register (MIAFTR), now run by the Motor Insurers’ Bureau as Vehicle Salvage and Theft Data. The entry also serves as their DVLA notification, under the ABI’s Salvage Code notification provisions.
The Institute of Automotive Engineer Assessors runs the Salvage Code exam that tests assessor competency.
Businesses can identify write-offs recorded on the register through Experian Condition Check, and salvage auction descriptions, damage details and available image links are accessible through SalvageGuide Salvage Check by registration or the SalvageGuide API. VIN-based workflows use SalvageGuide Salvage Check from VIN.
The scrapped marker is included in Experian Vehicle Identity, and Scrap Marker Check reports when a vehicle has been scrapped since your last check.
Where insurance write-off category data comes from
Insurer records and salvage auction records describe different events. Insurer records concern total-loss assessments; auction records concern vehicles offered for sale. The Motor Insurers’ Bureau (MIB) holds written-off and stolen-vehicle records in Vehicle Salvage and Theft Data, as MIB’s dataset policy explains.
Experian’s service accesses this insurer dataset, formerly MIAFTR, according to its Condition Check documentation.
One Auto API supplies write-off, salvage and category data through one API integration for insurers, dealers, finance businesses and salvage operators, supporting scrap and salvage use cases.
Frequently asked questions about insurance write-off categories
Is Category S or N worse?
Category S is the more serious marker, because the Association of British Insurers’ code reserves it for damage to the structural frame or chassis. Category S is also recorded on the replacement V5C, whereas a retained Category N vehicle can keep its existing logbook, according to GOV.UK. Businesses should review category data separately from registration documents.
What was a Category D write-off?
Category D was a repair-cost classification. The vehicle was cheaper to repair than replace, but the insurer wrote it off. Vehicles categorised under the old system retain their C or D labels, as Auto Trader confirms. Businesses should preserve that historical designation rather than automatically changing a database entry to N.
Can a Category S marker be removed?
Category S history stays on the record after repairs. The code restricts record changes or removal to correcting errors, with recategorisation permitted only in exceptional circumstances. Categorisation disputes go to an Appropriately Qualified Person for review, under the ABI’s Salvage Code procedures.
Build insurance write-off category checks into business decisions
Each write-off category should trigger a defined action in the buying, lending or underwriting process, such as rejection, further inspection or a valuation adjustment. Business teams should agree which category triggers which action before they integrate the data. Review the available write-off and condition data to identify the fields required for each buying, finance or insurance decision to identify risk and avoid paying more than a vehicle is worth.